

Financial First Responders: Preparing Communities for the Economic Shock of a Natural Disaster
Financial First Responders: Preparing Communities for the Economic Shock of a Natural Disaster
When a hurricane, wildfire, or flood strikes, the immediate focus is rightly on physical safety—evacuation, shelter, and medical care. But in the hours and days that follow, a second, less visible disaster unfolds: the economic shock. Lost documents, inaccessible bank accounts, sudden unemployment, and the daunting maze of insurance claims and federal aid can be overwhelming. This is where a new type of hero emerges: the Financial First Responder.
As the publishing arm of the National Association of Social Workers (NASW), naswpressonline.org provides expert resources that highlight the critical intersection of social well-being and economic stability. We understand that recovery is about more than rebuilding structures; it’s about rebuilding lives on a solid financial foundation. This article will break down the concept of Financial First Responders, explain why they are essential for equitable disaster recovery, and provide a roadmap for how we can all help prepare our communities for the inevitable financial aftershocks of a crisis.
Key Takeaways
- The economic shock of a natural disaster is often a “second disaster” that disproportionately harms vulnerable populations.
- “Financial First Responders” are trained professionals and volunteers—like social workers, financial counselors, and community leaders—who provide immediate financial guidance and support after a crisis.
- Social workers are uniquely equipped for this role due to their expertise in crisis intervention, resource navigation, and trauma-informed care.
- Community resilience depends on proactive preparation, including creating personal financial “go-bags” and establishing local response networks before a disaster strikes.
- Individuals, community organizations, and local governments all have a role to play in building a financially prepared community.
TL;DR
After a natural disaster, “Financial First Responders” are crucial guides who help individuals and families navigate the immediate economic chaos. This community-based approach, often led by social workers, is essential for an equitable and effective recovery.
Natural Disasters Inflict a Devastating “Second Disaster” Through Long-Term Economic Shock
Natural disasters inflict a devastating “second disaster” through long-term economic shock that disproportionately harms vulnerable populations. The visible destruction of a natural disaster is only the beginning of the crisis. The invisible, long-term financial fallout can trap families in a cycle of debt and poverty for years, derailing their stability and well-being long after the physical debris has been cleared. For many, this economic turmoil is more prolonged and damaging than the storm itself.
Beyond Physical Damage: The Hidden Financial Toll
The immediate aftermath of a disaster is a landscape of financial chaos. Survivors are often forced to make critical, long-term financial decisions while still processing the trauma of the event.
- Income Loss: Businesses are destroyed or forced to close temporarily, leading to immediate job and wage loss. After Hurricane Harvey, for example, an estimated 30% of workers in the most affected counties of Texas experienced job loss or reduced hours, according to a report by the Kaiser Family Foundation.
- Asset Destruction: The most significant assets for most families—their homes and vehicles—can be lost in an instant. Crucially, essential documents like birth certificates, Social Security cards, property deeds, and insurance policies are often destroyed, creating massive bureaucratic hurdles to recovery.
- Navigational Overload: The process of applying for aid from the Federal Emergency Management Agency (FEMA), filing insurance claims, and seeking assistance from non-profits is complex and exhausting. Survivors must become experts in bureaucracy overnight, often while lacking power, internet access, or even a permanent address.
- Increased Debt: With savings depleted and income gone, many families turn to credit cards or high-interest “disaster loans” to cover immediate needs like food, gas, and temporary lodging. This can initiate a debt spiral that persists for years.
The Ripple Effect on Community Economics
The financial shock doesn’t just impact individual households; it reverberates through the entire local economy, weakening the very systems people rely on for recovery.
- Business Closures: Small businesses are the backbone of local economies. According to FEMA, roughly 40 to 60 percent of small businesses never reopen their doors following a disaster. This loss cripples the local job market and tax base.
- Strained Public Services: As the tax base shrinks from business closures and property value decline, local governments face severe budget shortfalls. At the same time, the demand for social services, public health support, and infrastructure repair skyrockets, creating an unsustainable fiscal crisis.
- Housing Scarcity: When a disaster damages a significant portion of the housing stock, competition for the remaining safe and habitable units intensifies. This drives up rental prices and displaces residents, particularly low-income renters who may be forced to leave their communities permanently.
A “Financial First Responder” Guides Survivors Through the Economic Chaos
A “Financial First Responder” is a trained professional or community volunteer who provides immediate financial guidance and support in the chaotic aftermath of a disaster. Just as a paramedic provides medical triage on the scene of an accident, a Financial First Responder provides financial triage. They are the calm, knowledgeable guides who step into the chaos to help survivors make sound financial decisions when they are at their most vulnerable, stressed, and overwhelmed.
What Do Financial First Responders Actually Do?
Their role is practical, hands-on, and focused on immediate stabilization. They meet people where they are—in shelters, community centers, or mobile response units—to provide direct assistance.
- Triage & Prioritization: They help survivors answer the most urgent question: “What do I do right now?” This involves identifying immediate needs, such as accessing emergency cash, contacting employers, securing temporary housing, and replacing critical medications.
- Navigating Bureaucracy: They offer direct, hands-on assistance with filling out applications for FEMA Individual Assistance, Disaster Unemployment Assistance, and Small Business Administration (SBA) disaster loans. They help decipher confusing jargon and ensure paperwork is filed correctly to avoid delays.
- Advocacy & Communication: They empower survivors to communicate with financial institutions. This includes helping them contact their mortgage lender to request forbearance, call credit card companies to ask for deferred payments, and initiate the claims process with their insurance agent.
- Crisis Budgeting: They work with individuals and families to create a simple, short-term budget to manage limited resources. This helps stretch emergency funds and prioritize spending until more stable income or aid becomes available.
Who Can Be a Financial First Responder?
This role is not limited to one profession. A strong community network includes a variety of skilled individuals ready to help.
- Social Workers: With their training in crisis intervention and resource navigation, they are natural leaders in this field.
- Non-profit Financial Counselors: Professionals from accredited credit counseling agencies bring deep expertise in budgeting, debt management, and financial planning.
- Credit Union and Community Bank Staff: These local financial professionals understand the community’s economic landscape and can provide practical advice and services.
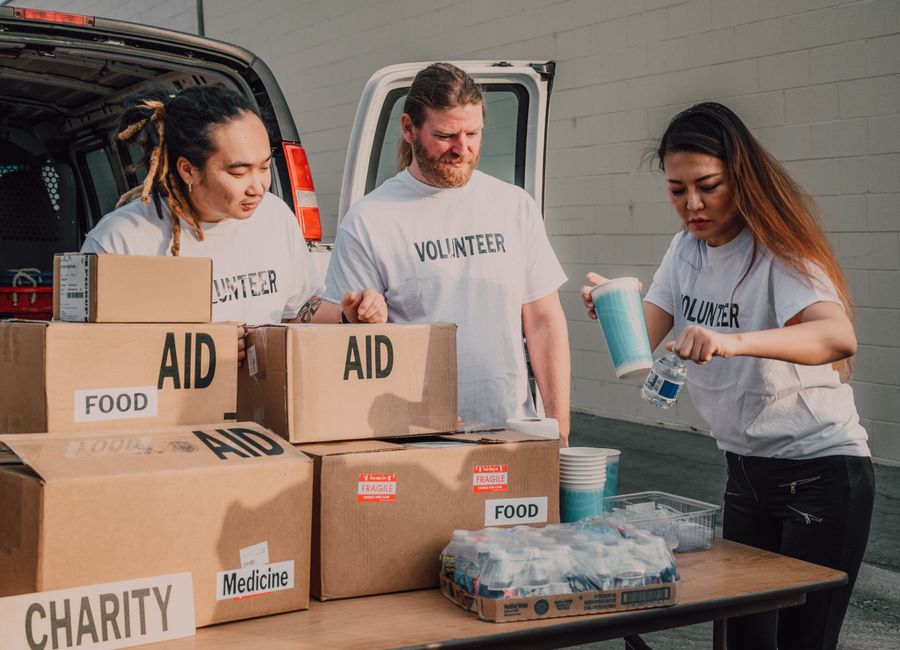
- Trained Volunteers: Organizations like the American Red Cross and United Way often train volunteers to provide financial guidance and case management in disaster recovery centers.
- Pro-bono Attorneys and Accountants: These professionals can volunteer their time to help with complex issues like property title disputes, tax implications of disaster aid, and contractor fraud.
Social Workers Are Uniquely Positioned to Act as Financial First Responders
Social workers are uniquely positioned to act as Financial First Responders due to their holistic training in crisis intervention, resource navigation, and advocacy for equity. The work of a Financial First Responder is about more than just numbers on a spreadsheet; it’s about understanding the profound human element of a financial crisis. This is the core of the social work profession, making social workers indispensable leaders in disaster-related economic recovery.
The Social Work Skillset in Action
The principles of social work are directly applicable to the financial chaos following a disaster.
- Trauma-Informed Approach: Social workers are trained to recognize that financial distress is a form of trauma. They approach survivors with empathy, patience, and an understanding that the ability to process complex information is diminished during a crisis. They create a safe, non-judgmental space for people to make decisions.
- Person-in-Environment Perspective: This core social work principle involves understanding how a person’s family, community, and larger societal factors impact their ability to recover. A social worker doesn’t just see a financial problem; they see a whole person dealing with housing instability, potential health issues, childcare challenges, and systemic barriers that may make their recovery more difficult.
- Resource Navigation: Social workers are masters of connection. They are experts at linking people to a complex web of local, state, and federal resources that go far beyond just financial aid, including mental health services, long-term housing solutions, and legal aid.
How NASW Press Supports This Work
As the premier publisher for the social work profession, naswpressonline.org is committed to advancing this critical work. We offer an extensive catalog of books and resources on financial social work, disaster management, and community practice. These materials equip professionals with the evidence-based strategies and ethical frameworks needed to effectively serve as Financial First Responders and build long-term community resilience.
Proactive Community-Level Preparation Is the Most Effective Defense
Proactive community-level preparation is the most effective way to mitigate the economic shock of a natural disaster before it strikes. Waiting until the emergency alert sounds to think about financial recovery is far too late. Resilient communities build systems and empower individuals with the tools and knowledge they need to withstand an economic shock long before the storm clouds gather.
For Individuals & Families: Your Financial “Go-Bag”
Every household should have a financial “go-bag” ready alongside their emergency kit. This is a collection of essential documents that will be critical for recovery. Store them in a waterproof, fireproof bag or a secure, password-protected digital folder.
- Identification: Copies of driver’s licenses, birth certificates, Social Security cards, and passports.
- Property Documents: Copies of property deeds or titles, rental agreements, and vehicle registrations.
- Insurance Policies: A list of all policies (home, auto, flood, life) with policy numbers and the contact information for your agents.
- Financial Records: A list of all credit card, bank, and loan accounts with account numbers and customer service phone numbers.
- Emergency Cash: A small amount of cash in small bills, as ATMs and credit card systems may be down for days.
For Community Organizations & Local Governments: Creating a Response Network
Individual preparedness is vital, but a coordinated community response is what truly builds resilience.
- Pre-Disaster Pacts: Local governments can establish formal partnerships between non-profits, financial institutions (especially community banks and credit unions), and social service agencies. This ensures a coordinated, non-duplicative response when a disaster hits.
- Resource Mapping: Create and publicize a simple, accessible directory of trusted local financial resources and designated “Financial First Responders.” This list should be available online and in print at public locations like libraries and community centers.
- Public Education Campaigns: Host free community workshops on topics like creating a financial go-bag, understanding flood insurance, and avoiding post-disaster scams and contractor fraud.
Take Concrete Steps Today to Prepare for a Disaster’s Financial Impact
Financial readiness is an active process, not a passive state. Whether you are preparing your own household or advocating for your entire town, the actions you take now can make a monumental difference when a crisis occurs.
Step 1: Assess Your Personal Financial Readiness
- Build your financial go-bag this week. Use the checklist above and gather your documents. Don’t wait.
- Review your insurance coverage. Read your homeowner’s or renter’s policy carefully. Do you have enough coverage to rebuild? Crucially, understand that standard policies do not cover flooding; this requires a separate policy. A thorough review of your homeowner’s insurance can be a critical first step in protecting your largest asset.
- Start a small emergency savings fund. Even if it’s just $5 a week, having liquid cash available is essential. Automate a transfer to a separate savings account to make it effortless.
Step 2: Identify Your Local Support Systems
- Know your numbers. Look up your local 2-1-1 service, which is a free, confidential information and referral service. Find your local United Way or community action agency. Save these numbers in your phone’s contacts right now.
- Find a CDFI. Find out which local banks or credit unions are designated as Community Development Financial Institutions (CDFIs). These institutions have a mission to serve low- and moderate-income communities and often have special programs and more flexible terms for those in crisis.
Step 3: Advocate for Community Preparedness
- Ask questions. Attend a town hall meeting or contact your local elected officials or emergency management office. Ask them: “What is our community’s plan for economic recovery after a disaster? Who are our designated Financial First Responders?”
- Get involved. Volunteer with or donate to local organizations that provide financial counseling or disaster relief. Your time and resources can help build the infrastructure needed to support your neighbors in a time of crisis.
Building Resilience Together
The economic shock of a natural disaster is a community-wide problem that demands a community-wide solution. The concept of Financial First Responders moves us beyond a focus on individual responsibility and toward a model of collective care and organized, compassionate support. By empowering professionals like social workers, training dedicated volunteers, and preparing our systems ahead of time, we can build communities that are not just prepared to survive, but equipped to recover with equity and dignity. When disaster strikes, this network ensures that no one has to navigate the financial aftermath alone.
Ready to learn more about the vital role social work plays in building strong, resilient communities? Explore the expert publications and professional development resources available at naswpressonline.org.
Frequently Asked Questions
What is a ‘Financial First Responder’?
What is the ‘economic shock’ that happens after a natural disaster?
Why are Financial First Responders considered essential for disaster recovery?
Who is most affected by the financial aftermath of a natural disaster?